

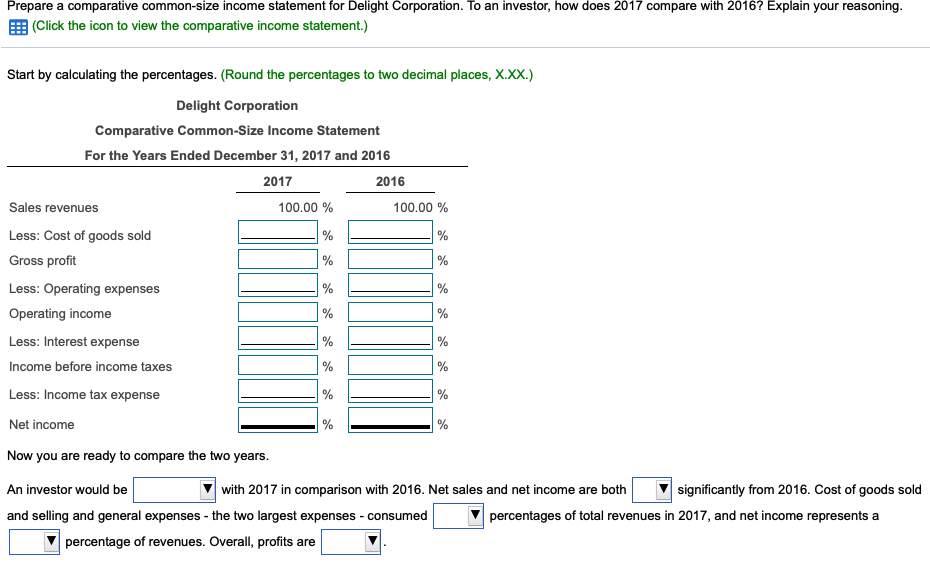
On the other hand, a common size financial statement presents all items in percentage terms. It includes assets, liabilities, and sales as percentages, enabling a detailed analysis of each line item relative to the base amount for the given accounting period. Comparative financial statements present the same company’s financial statements for one or two successive periods in side-by-side columns. The calculation of dollar changes or percentage changes in the statement items or totals is horizontal analysis.
- Cash ranges between 5% and 8.5% of total assets and short-term debt accounts for about 5% of total assets over the two years.
- Common-size Statements are accounting statements expressed in percentage of some base rather than rupees.
- It helps in easy analysis of trends and, as such, is also known as Trend Analysis.
- The steps mentioned above are used to prepare the common size income statement of any business.
How does a common size income statement aid in financial comparisons?
Using common-size financial statements helps spot trends that a raw financial statement may not uncover. When you show the items on the income statement as a percentage of the sales figure, it makes it easier to compare the income and expenses and understand the financial position of the company. Common size analysis is an excellent tool to compare companies of different sizes or to compare different years of data for the same company, as in the example below. Another technique that exhibits Comparative Income Statement in terms of the relative size of line items is the Vertical Analysis. This technique enables easy comparison of Income statements of companies of different sizes.
Common size cash flow statement analysis
Doing so will help you see at a glance which expenses take up the largest percentage of your revenue. It standardizes financial data, allowing businesses to compare performance across different periods or with other companies, regardless of size. As you can see from Figure 13.6, the composition of assets, liabilities, and shareholders’ equity accounts changed from 2009 to 2010. Let us try to undestand the concept of common size income statement interpretation with the help of some suitable examples. Let us go through the disadvantages of the concept of comparative income statement in management accounting in detail.
Common Size Financial Statements in Detail
COGS divided by $100,000 is 50%, operating profit divided by $100,000 is 40%, and net income divided by $100,000 is 32%. As we can see, gross margin is 50%, operating margin is 40%, and the net profit margin is 32%–the common size income statement figures. It’s important to note that the common size calculation is the same as calculating a company’s margins. The net profit margin is simply net income divided by sales revenue, which happens to be a common-size analysis. Common size income statements with easy-to-read percentages allow for more consistent and comparable financial statement analysis over time and between competitors. With a common size horizontal analysis, you can easily see if, for example, your expenses increased as a percentage of revenue, stayed the same or decreased among different time periods.
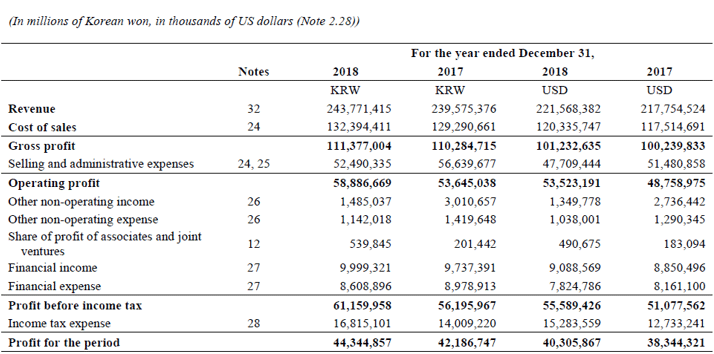
Now that we have an understanding of Comparative Financial Statements and Common Size Financial Statements, let’s delve into the key differences between these two financial analysis tools. This tool is especially important if you’re using key performance indicators to comparative common size income statement measure your business’s performance and profitability. The approach lets you compare your business to your competitors’ businesses, regardless of size differences. It provides a clear view of financial ratios, aiding in strategic planning and resource allocation.
What Is the Main Purpose of Common-Size Financial Statements?
The common size percentages also help to show how each line item or component affects the financial position of the company. As a result, the financial statement user can more easily compare the financial performance to the company’s peers. Although common-size balance sheets are most typically utilized by internal management, they also provide useful information to external parties, including independent auditors. The most valuable aspect of a common size balance sheet is that it supports ease of comparability. The common size balance sheet shows the makeup of a company’s various assets and liabilities through the presentation of percentages, in addition to absolute dollar values. This affords the ability to quickly compare the historical trend of various line items or categories and provides a baseline for comparison of two firms of different market capitalizations.
It precisely matches the common-size analysis from an income statement perspective. Share repurchase activity can also be considered a percent of the total top line. Debt issuance is another important figure in proportion to the amount of annual sales it helps to generate. These items are calculated as a percentage of sales so they help indicate how much the company uses them to generate overall revenue.
As you can see in Figure 13.5, Coca-Cola’s gross margin as a percent of net sales decreased from 2009 to 2010 (64.2 percent versus 63.9 percent). Income before taxes increased significantly from 28.6 percent in 2009 to 40.4 percent in 2010, again mainly due to a one-time gain of $4,978,000,000 in 2010. This caused net income to increase as well, from 22.0 percent in 2009 to 33.6 percent in 2010. In the expense category, cost of goods sold as a percent of net sales increased, as did other operating expenses, interest expense, and income tax expense. Selling and administrative expenses increased from 36.7 percent in 2009 to 37.5 percent in 2010. Common Size Income Statement presents every line item available in the company’s income statement in the form of the relative percentage of sales.
Therefore, along with reporting the dollar amount of cash, the common size financial statement includes a column that reports that cash represents 12.5% ($1 million divided by $8 million) of total assets. A common size balance sheet is a balance sheet that displays both the numeric value and relative percentage for total assets, total liabilities, and equity accounts. Common size balance sheets are used by internal and external analysts and are not a reporting requirement of generally accepted accounting principles (GAAP).
It provides investors with a clear picture of a company’s financial health and efficiency. Note that although we have compared just two years of data for Charlie and Clear Lake, it is more common to use several years of data to get a more robust view of long-term trends. First, the cost of goods sold (COGS) for the business firm has increased from Year 1 to Year 2. The COGS usually includes direct labor costs and the cost of direct materials used in production.